Blog Flux Directory Subscribe in NewsGator Online Subscribe with Bloglines http://www.wikio.com Blog directory
And, yes, I DO take it personally
Mandy: Great blog!
Mark: Thanks to all the contributors on this blog. When I want to get information on the events that really matter, I come here.
Penny: I'm glad I found your blog (from a comment on Think Progress), it's comprehensive and very insightful.
Eric: Nice site....I enjoyed it and will be back.
nora kelly: I enjoy your site. Keep it up! I particularly like your insights on Latin America.
Alison: Loquacious as ever with a touch of elegance -- & right on target as usual!
"Everybody's worried about stopping terrorism. Well, there's a really easy way: stop participating in it."
- Noam Chomsky
Send tips and other comments to: profmarcus2010@yahoo.com

And, yes, I DO take it personally

Friday, September 02, 2011

Suing the banks - about freakin' time...!

more like this...
U.S. Is Set to Sue a Dozen Big Banks Over Mortgages

The federal agency that oversees the mortgage giants Fannie Mae and Freddie Mac is set to file suits against more than a dozen big banks, accusing them of misrepresenting the quality of mortgage securities they assembled and sold at the height of the housing bubble, and seeking billions of dollars in compensation.

The Federal Housing Finance Agency suits, which are expected to be filed in the coming days in federal court, are aimed at Bank of America, JPMorgan Chase, Goldman Sachs and Deutsche Bank, among others, according to three individuals briefed on the matter.

The suits stem from subpoenas the finance agency issued to banks a year ago. If the case is not filed Friday, they said, it will come Tuesday, shortly before a deadline expires for the housing agency to file claims.

it's 1:45 a.m... i fell asleep around 6 p.m. with my clothes on and am just now getting up to go back to bed... still recovering from jet-lag, i guess...

anywayz...

doing a late-night email check, i ran across the above, guaranteed to put a smile on my face... how sad that even the slightest evidence of any accountability whatsoever can make my heart flutter...

Labels: , , , , , , , , ,

Submit To Propeller


[Permalink] 0 comments

Monday, January 24, 2011

Of COURSE the mortgage giants are sticking it to us even more than we thought...!

why would we think for a moment that they would do otherwise...? privatize profits, socialize costs - that's the american way of capitalism... bend over and grab your ankles...
Mortgage Giants Leave Legal Bills to the Taxpayers

Since the government took over Fannie Mae and Freddie Mac, taxpayers have spent more than $160 million defending the mortgage finance companies and their former top executives in civil lawsuits accusing them of fraud. The cost was a closely guarded secret until last week, when the companies and their regulator produced an accounting at the request of Congress.

The bulk of those expenditures — $132 million — went to defend Fannie Mae and its officials in various securities suits and government investigations into accounting irregularities that occurred years before the subprime lending crisis erupted. The legal payments show no sign of abating.

of COURSE it was "a closely guarded secret"... why make a big deal out of announcing that our routine screwing is even more painful than we already thought...?

Labels: , , , , ,

Submit To Propeller


[Permalink] 0 comments

Thursday, April 23, 2009

Anybody who thinks the economy is improving, raise your hand

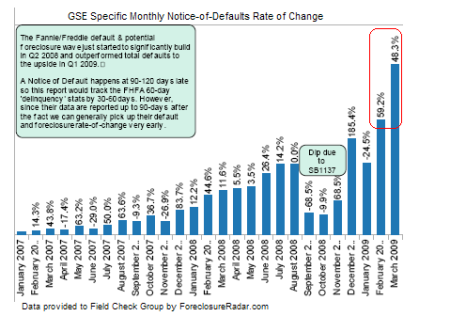
< sound of loud gong > WRONG...! mortgage delinquencies rising FIFTY PERCENT IN ONE MONTH ain't an economy on the mend...

bloomberg
via mish's global economic trend analysis...

Fannie Mae and Freddie Mac mortgage delinquencies among the most creditworthy homeowners rose 50 percent in a month as borrowers said drops in income or too much debt caused them to fall behind, according to data from federal regulators.

The number of so-called prime borrowers at least 60 days behind on mortgages owned or guaranteed by the companies rose to 743,686 in January, from 497,131 in December, and is almost double the total for October, the Federal Housing Finance Agency said in a report to Congress today.

Of all borrowers who ended up in default, 34 percent told Fannie and Freddie they were earning less money, about 20 percent cited excessive debt as a reason for missing mortgage payments, and 8.1 percent blamed unemployment, FHFA said.

just in case you didn't grab it on the first read-through, that's fifty percent among the MOST CREDITWORTHY HOMEOWNERS...!

let the chart tell the story...


Photobucket

Labels: , , , , , , ,

Submit To Propeller


[Permalink] 0 comments

Wednesday, April 22, 2009

Meanwhile, in the "are you shitting me" department...

ya know, i read a headline like this and i just have to shake my head...
Acting CFO of Freddie Mac Found Dead in Apparent Suicide
The acting chief financial officer of troubled mortgage giant Freddie Mac committed suicide overnight in his Vienna home, Fairfax police said this morning. David Kellermann, 41, has been Freddie Mac's chief financial officer since September. His body was found in the 1700 block of Raleigh Hill Road.

once upon a time, i might have believed a story like this... now...? you gotta be shittin' me...

Labels: , , ,

Submit To Propeller


[Permalink] 0 comments

Thursday, September 18, 2008

"Negates its fundamental principles in its behavior" - HAHAHAHAHA...! < cough, snort > HAHAHAHA...!

< wipes tears from eyes >
Is the United States no longer the global beacon of unfettered, free-market capitalism?

In extending a last-minute $85 billion lifeline to American International Group, the troubled insurer, Washington has not only turned away from decades of rhetoric about the virtues of the free market and the dangers of government intervention, but it has also probably undercut future American efforts to promote such policies abroad.

“I fear the government has passed the point of no return,” said Ron Chernow, a leading American financial historian. “We have the irony of a free-market administration doing things that the most liberal Democratic administration would never have been doing in its wildest dreams.”

The bailout package for A.I.G., on top of earlier government support for Bear Stearns, Fannie Mae and Freddie Mac, has stunned even European policy makers accustomed to government intervention — even as they acknowledge the shock of the collapse of Lehman Brothers.

“For opponents of free markets in Europe and elsewhere, this is a wonderful opportunity to invoke the American example,” said Mario Monti, the former antitrust chief at the European Commission. “They will say that even the standard-bearer of the market economy, the United States, negates its fundamental principles in its behavior.”

not that the u.s. hasn't been the master of hypocrisy right along, but these last few weeks have put it right up there in neon lights for all to see...

Labels: , , , , , , , , ,

Submit To Propeller


[Permalink] 0 comments

Monday, September 15, 2008

C'mon, dammit, let's let the friggin' house of cards FALL already...!

geeeez, louise...! get 'er done, will ya...?

Photobucket

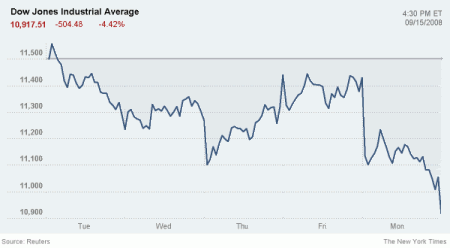
The churn of a rapidly changing financial landscape left Wall Street cold on Monday, as a late afternoon sell-off sent the stock market to its worst daily loss in seven years.

The Dow Jones industrial average plummeted more than 500 points
— its worst session since the days after the Sept. 11, 2001 terrorist attacks.

The blue-chip index spent the entire day in negative territory, but the losses did not begin approaching dramatic levels until late in the afternoon. In the last 30 minutes of trading, investors seemed to give in to their fears about the health of the financial system, sparking a wave of selling that sent the Dow, already about 300 points lower, to a 504.48 point decline for the day.

The Standard & Poor’s 500-stock index fared even worse, losing 4.7 percent, and the technology-heavy Nasdaq composite index fell 3.2 percent. In Europe, benchmark stock indexes were off nearly 4 percent in London and Paris and almost 3 percent in Frankfurt.

meanwhile, hank paulson, the flaming bush mouthpiece that he is, tries to pour oil on the troubled waters...
In a briefing in Washington, Treasury Secretary Henry M. Paulson Jr. said the financial markets were going through a tough time “as we work off some of the past excesses,” but that Americans could “remain confident in the soundness and the resilience of our financial system.”

“Let me step back a bit and provide a little perspective,” Mr. Paulson said. “As I’ve long said, the housing correction is at the root of the challenges facing our markets and our financial institutions. I believe that we’ve taken very important steps with respect to Fannie Mae and Freddie Mac, and they’re amongst the most important actions we can take to work through this turmoil.”

if hankie-poo is expecting us to swallow that enormous load of fresh, steaming shit, when every time we've watched yet another financial bridge burn in the past nine months, he's said the very same goddam thing, and, each time, the next bridge that catches fire is a bigger bridge and the span of water that it crosses is increadingly unnavigable, i ain't buyin' a single goddam syllable that passes his lying lips...

Labels: , , , , , , ,

Submit To Propeller


[Permalink] 0 comments

Sunday, September 07, 2008

Jerome a Paris 'splains what we taxpayers just won in the latest Bush flim-flam

as good an explanation as i've seen...

As expected, as the government takes over, the normal shareholders are wiped out, something that will allow the Bush administration to claim that they are being tough and not bailing out investors, but we'll see that this claim is fundamentally false.

This whole side of the package will allow the government to claim that the bailout has a minimal cost: $1 billion only for now, a highly disingenuous claim (the warrants will most likely need to be exercised - but only next year, and there is the rest...)

The plan, outlined jointly by the Treasury Department and Federal Housing Finance Agency, also includes a plan for the Treasury to purchase mortgage-backed securities from the firms in the open market, and a lending facility through the Treasury from its general fund held at the Federal Reserve Bank of New York.

This is huge. This is the federal government taking over the "toxic waste" in a way that will have an impact not just on Freddie and Fannie, but on the whole market. By "buying" mortgage-backed securities instrad of taking them as collateral, the Treasury does two things at the same time:

  • it takes off the assets and liabilities off the balance sheet of the two companies in a definitive way (rather than temporarily) and assumes, for sure, the associated risk;

  • it sets a price on these securities. This has been the biggest problem to solve the credit crisis: nobody has been willing to set a price on these assets, because of the uncertainty on the real value of the underlying assets (or because everybody could see that they were falling by the day). By setting such a price, thegovernment creates a highly significant precedent - and, in all likelihood, provides a floor to these prices, ie an implicit commitment (or at least the expectation of a commitment) to buy more such securities.

In doing this, the government is boldly trying to call the end of the financial crisis, set a total price to it, and agree to pay the difference if the cost is higher in the end. This, to me, looks like a full governmental guarantee to the whole banking sector. Of course, a lot will depend on where the price is set to purchase these mortgage-backed assets, but this is still a take-over of the toxic waste by taxpayers, at aprice that may or may not (and, frankly, is highly unlikely to) be right.

But it's even worse than that: by providing an additional lending facility on top of that, the government is saying: we're putting our money (well, yours) where our mouth is - providing further liquidity to the companies and, I presume, expecting them, once the toxic waste has been cleared from their books (which can happen now that there is a floor price), to lend to the mortagage markets again.

It's the usual solution of the Greenspan bubble: as soon as one bursts, we blow another one to cover it up and keep the party going a little longer.

Of course, the goal here is simply to create a boost that lasts until November, and given the kind of weaons used, it's likely to succeed in that short term goal. Saving the US economy is another thing, given that its fundamental problem is spending beyond incomes - more debt does not cure that, rather the opposite. The twin movements of growing spending and stagnant incomes have to be brought back together. Boosting spending via debt cannot work this time; incomes have to be raised - and for the right people.

This plan is not about this, it's about bailing out the financiers that played and lost with other people's money, and give them a chance to try again. Par for the course, of course.


well, she-e-e-e-e-it, vern, we KNEW this deal wasn't crafted to benefit us, the poor slobs who have our pockets picked on a daily basis to keep the stretch limos and private jets of the bigshots topped off with ever-more-expensive fossil fuel... but it's always nice when someone who has just a bit of a CLUE explains it to those like me who can very quickly recognize the smell of fresh manure even if we don't know its chemical composition...

Labels: , , , , , ,

Submit To Propeller


[Permalink] 0 comments

Fannie and Freddie now belong to US and WE will "provide as much capital as they need"

hold on to your wallets... here it comes... oh, and btw, check out where the new ceo of freddie hails from - the carlyle group... ain't THAT an interestin' coincidence...?!?!
The Treasury Department seized control of Fannie Mae and Freddie Mac, the nation’s giant quasi-public mortgage finance companies, and announced a four-part rescue plan that includes an open-ended guarantee from the Treasury Department to provide as much capital as they need to stave off insolvency.

At a news conference on Sunday morning, Treasury Secretary Henry M. Paulson Jr. also announced that he had dismissed the chief executives of both companies and replaced them with two long-time financial executives. Herbert M. Allison, currently chairman of TIAA-CREF, the huge pension fund for teachers, will take over Fannie Mae and replace the chief executive, Daniel Mudd. David M. Moffett, currently a senior adviser at the Carlyle Group, one of the country’s biggest private equity firms, will replace Richard Syron as chief executive of Freddie Mac.

“Fannie Mae and Freddie Mac are so large and so interwoven in our financial system that a failure of either of them would cause great turmoil in our financial markets here at home and around the globe,” Mr. Paulson said. “This turmoil would directly and negatively impact household wealth: from family budgets, to home values, to savings for college and retirement. A failure would affect the ability of Americans to get home loans, auto loans and other consumer credit and business finance. And a failure would be harmful to economic growth and job creation.”

Mr. Paulson refused to say how much capital the government might eventually have to provide, or what the ultimate cost to taxpayers might be.

The companies are likely to need tens of billions of dollars over the next year, but the utlimate cost to taxpayers will largely depend on how and how fast the housing and mortgage markets recover from their current crisis.

of COURSE paulson refused to say how much the ultimate cost to the taxpayers might be... if he even hazarded an extremely conservative, low-end guess, american citizens would be out marching in the streets (which is what we SHOULD have been doing for the past two years)...

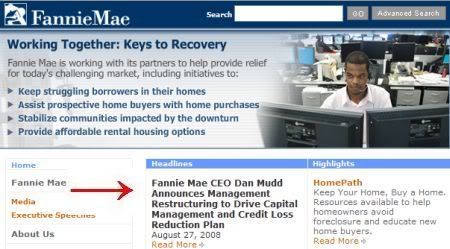
oh, yeah, and as of 10:30 a.m. pacific time this morning, fannie's website was still touting all the good stuff being worked on by the now-axed dan mudd...


Photobucket

Labels: , , , , , ,

Submit To Propeller


[Permalink] 0 comments

Friday, September 05, 2008

Fannie Mae and Freddie Mac to be nationalized

here we go... the house of cards is comin' down...
Senior officials from the Bush administration and the Federal Reserve on Friday informed top executives of Fannie Mae and Freddie Mac, the mortgage-finance giants, that the government is preparing a plan to seize the two companies and place them in a conservatorship, officials and company executives briefed on the discussions said.

The plan, effectively a government bailout, was outlined in separate meetings that the chief executives were summoned to attend on Friday at the office of the companies’ new regulator. The executives were told that under the plan, they and their boards would be replaced, and their shareholders virtually wiped out, but that the companies would be able to continue functioning with the government generally standing behind their debt, people briefed on the discussions said.

It is not possible to calculate the cost of any government bailout, but the huge potential liabilities of the companies could cost taxpayers tens of billions of dollars and make any rescue among the largest in United States history.

there's no way to overstate how big this is... simply put, it's HUGE... and, if our esteemed government has its way, it's us, joe and jane schmoe taxpayer, who will be the ones to pay...

Labels: , , , , , ,

Submit To Propeller


[Permalink] 0 comments

Thursday, February 07, 2008

Worthless economic stimulus plan passes

oh, lovely... i'm going to sit down right now and write up a list of everything i'm going to buy with my $600 or whatever they're going to throw at me to help me continue to pretend that we're not being taken to the cleaners by crooks...
The Senate overwhelmingly approved a $171 billion economic stimulus program on Thursday afternoon, sending it to the House for final passage on Thursday evening so that it can be sent quickly to President Bush’s desk.

The 81-to-16 vote came after Senate Democrats agreed to add only payments for senior citizens and disabled veterans to a package already approved overwhelmingly by the House with the backing of President Bush. The Democratic senators had wanted to add more than $40 billion to the House version, a proposal that would have brought the cost of the package to about $204 billion over two years.

But Republican senators held firm, frustrating the Democrats’ efforts to get the 60 votes they needed to end debate. But in settling for a $171 billion package, the Senate Democratic majority leader, Harry Reid of Nevada, refused to admit defeat.

“We were able to make the House bill better,” he said, pledging to continue to try to corral enough votes to provide more economic stimulus in the months ahead.

“Discretion is the better part of valor,” said Senator Max Baucus, Democrat of Montana and chairman of the Senate Finance Committee.

“The best thing for us to do is declare a big victory that we’ve achieved, namely getting the rebate checks to 20 million seniors and 250,000 disabled veterans,” Mr. Baucus said.

As passed by the Senate and sent to the House, the program calls for rebates ranging from $300 to $1,200 for most taxpayers, payments of $300 to people who paid no income taxes but earned $3,000 or more from Social Security or veterans’ disability benefits, and various tax incentives for businesses.

i posted on this disgusting scam the other day... like i keep saying, ferchrissake, let's let the whole goddam thing collapse under its own corrupt weight...

Labels: , , , , , , , , , ,

Submit To Propeller


[Permalink] 0 comments

Wednesday, February 06, 2008

The economic stimulus plan will - no surprise - benefit the super-rich

and leave us peasants - also no surprise - holding the bag...
Congress is about to sell us the biggest fraud in American history.

It's been highly touted as an economic stimulus bill that will help millions of Americans - and has the backing of both President Bush and House Speaker Nancy Pelosi. In the coming year, individuals would receive rebates of up to $600 and families up to $1,200. There are other goodies, too, including tax write-offs for small businesses and an expansion of the child tax credit.

But, as the old adage goes, nothing comes for free. As part of the bill, Congress is set to rush through an increase in the mortgage loan limits for Fannie Mae and Freddie Mac (and Federal Housing Administration insurance, too) - from $417,000 to $729,750 - the first step toward a massive financial disaster in which taxpayers will end up paying through the nose.

Here's how we got to this point. Domestic and international investors hold hundreds of billions of dollars in bad debt, because U.S. investment houses sold them junk securities based on often fraudulent mortgages. Many of these mortgages were sold to unqualified buyers under terms that made widespread foreclosures a certainty once the housing market began to fall.

Investment banks and bond rating agencies sat down and tried to figure out how to describe Americans with insufficient incomes and little for a down payment as great credit risks on loans too big for their incomes. The new rules focused on credit scores, because it was a good excuse to avoid looking at income and down payment, factors that would have restricted this moneymaking fiasco.

Now, thanks to Congress, junk bond investors will be able to pawn off their bad debt to Fannie and Freddie, instead of suing the big investment houses for ripping them off. This shift will certainly doom Fannie Mae and Freddie Mac, so don't be surprised if we, the taxpayers, have to bail out poor Fannie and Freddie - to the tune of more than $1 trillion.

would we have expected anything less from the criminals that run our government...?

Labels: , , , , , , , , ,

Submit To Propeller


[Permalink] 0 comments