Blog Flux Directory Subscribe in NewsGator Online Subscribe with Bloglines http://www.wikio.com Blog directory
And, yes, I DO take it personally
Mandy: Great blog!
Mark: Thanks to all the contributors on this blog. When I want to get information on the events that really matter, I come here.
Penny: I'm glad I found your blog (from a comment on Think Progress), it's comprehensive and very insightful.
Eric: Nice site....I enjoyed it and will be back.
nora kelly: I enjoy your site. Keep it up! I particularly like your insights on Latin America.
Alison: Loquacious as ever with a touch of elegance -- & right on target as usual!
"Everybody's worried about stopping terrorism. Well, there's a really easy way: stop participating in it."
- Noam Chomsky
Send tips and other comments to: profmarcus2010@yahoo.com

And, yes, I DO take it personally

Monday, June 25, 2012

Another Euro Zone country falls to its knees

from the ft...

Cyprus requests eurozone bailout


Cyprus has become the latest eurozone country to seek a bailout amid mounting economic problems and fresh challenges for its banks after a credit rating agency downgrade.

Bowing to eurozone pressure, the government of President Demetris Christofias said it had asked for help, just days before a deadline to recapitalise one of the country’s largest banks.

Cyprus is seeking financial help from the European Financial Stability Facility or its successor, the European Stability Mechanism, a government statement said on Monday. “The purpose of the required assistance is to contain the risks to the Cypriot economy, notably those arising from the negative spillover effects through its financial sector, due to its large exposure in the Greek economy,” the government said.

they're dropping like flies...

Labels: , , , , , ,

Submit To Propeller


[Permalink] 0 comments

Saturday, June 16, 2012

The crisis in Europe - in Spain and Greece, the rich get a LOT richer

disaster capitalism continues to run amok...

Who Profits?

Austerity, Greed & the Pain in Spain

Nobel Laureate economist Joseph Stiglitz characterizes the Spanish bank bailout as “voodoo economics” that is certain “to “fail.” New York Times economic analyst Andrew Ross Sorkin agrees: “By now it should be apparent that the bailout has failed—or at least on its way to failing.” And columnist and Nobel Prize-winning economist Paul Krugman bemoans that Europe (and the U.S.) “are repeating ancient mistakes” and asks, “why does no one learn from them?”

[...]

If you work at a regular job, you are in deep trouble. Spanish unemployment is at 25 percent—much higher in the country’s southern regions—and 50 percent among young people. In one way or other, those figures—albeit not quite as high—are replicated across the Euro Zone, particularly in those countries that have sipped from Circe’s bailout cup: Ireland, Portugal, and Greece.

But if you are Josef Ackermann heading up the Deutsche Bank, you earned an 8 million Euro bonus in 2012, because you successfully manipulated the past four years of economic meltdown to make the bank bigger and more powerful than it was before the 2008 crash. In 2009, when people were losing their jobs, their homes, and their pensions, Deutsche Bank’s profits soared 67 percent, eventually raking in almost 8 billion Euros for 2011. The bank took a hit in 2012, but the Spanish bailout will help recoup Deutsche Bank’s losses from its gambling spree in Spanish real estate.

[...]

All over the world, capital is on the march, with the goal of rolling back the social programs of the post-World War II period and returning to the Gilded Age when the rich did pretty much as they pleased.
 
Weakening unions is central to this, as is privatizing everything capital can get its hands on, and the economic crisis is the perfect cover to try an accomplish this.

[...]

So, the answer to Krugman’s question, “why are they repeating ancient mistakes?”

Because they are making out like bandits.

as in spain, so in greece... the rich make out like bandits while the masses suck hind tit...

Greece: What Can be Done?

Greece faces the unenviable choice between accepting the terms of “the Troika” [the European Union, European Central Bank, and International Monetary Fund] and facing the continuation and deepening of a socio-economic crises, which includes five years of negative growth, over 23% unemployment, an astronomical rise in poverty (from less than 15% to over 40%) and mounting suicides, or a rejection of the “memorandum”, and a likely cut-off of Eurozone funding and capital markets with virtually few reserves toc over salaries, pensions or public services.

[...]

Greece, during its 30 year membership in the European Union actually saw its meager and backward manufacturing and agricultural base shrink, in the face of cheap and better imports from developed capitalist countries like Germany, France, Holland and elsewhere. Unlike Argentina, Greece received billions of dollars in “transfers,” compensation funds to upgrade its economy and competitiveness and prepare it for full integration (lowering of tariff barriers). However, the “transfers” were not channeled into productive activity either by the two ruling parties or by the ‘capitalists’ and ‘farmers.’ The ruling parties used the transfers to build extensive electoral patronage machines; they squandered funds for overpriced state contracts to provide builders engaged in non-productive building projects (including the multi-billion dollar swindle around the Olympic Games). Tens of thousands of unemployed graduates and party loyalists bloated the national, regional and local bureaucracy, increasing consumption, blocking any meaningful productive activity.

Capitalists designed “productive projects and then transferred EU loans and handouts to local and overseas real estate investments and luxury purchases. The Greek elite transferred loans to London, Swiss and Cypriot bank accounts – while the government signed off as ultimate guarantor.

[...]

Most important, the economic elite – bankers, ship owners, construction-real estate – politicians, speculators skimmed off billions from the EEC transfers in the form of illicit loans to cronies and in the form of fees, management charges for credit dealings and pension funding.

The European bankers, government officials and exporters were acutely aware that the “transfers” were being pillaged – but they went along, for obvious reasons of economic and political gain: lucrative interest payments flowed into their coffers; exporters took over Greek consumer markets; bankers and investment houses found willing pension fund managers ‘open’ to dubious investments. Even tourists enjoyed the sun and imports which reminded them of home: wiener schnitzel, English ale, Dutch feta. Moreover, Greece spent 15% of its budget on the military, serving NATO goals and bases.

[...]

Any road map out of the Greek crises will be difficult, complex, and arduous – given the “scorched earth” economy which a left government (LG) will inherit. The first and most basic concern of a LG is to end the policies and especially the agreements with the “Troika” that demand further mass firings of public employees, the reduction in social services, the cuts in minimum wages and pensions. A new LG needs to impose a series of emergency measures to avoid economic bankruptcy.

It is absolutely clear that European bankers and regimes want to punish Greece for transgressions of their “austerity pact.” If Greece should succeed in renouncing the austerity pact, the Euro bankers fear that other countries – Spain, Portugal, Italy, Cyprus and Ireland might follow suit.

Greece should suspend debt payments, impose tight capital controls and freeze bank deposits to avoid capital flight, in the face of the Troika cut-off of funding. The LG should convoke a series of emergency commissions to (1) secure alternative sources of emergency financing from several reserve funds with Euro holdings. They must seek loans from Russia, Iran, Venezuela, China and other states not beholden to the Troika and (2) make an inventory of available and potential productive enterprises – bankrupt or troubled firms, indebted enterprises – and convert them into state sponsored worker-employee operated co-operatives (3) investigate public debt to determine what can be classified as ‘legitimate’(loans channeled into productive employment) or illegitimate (loans that enriched speculators, corrupt contractors, political leaders) (4) investigate and attach overseas holdings of wealthy Greeks who were engaged in multi-year multi-million tax evasion and who accumulated illicit income via unpaid loans and money laundering. Greek auditors should proceed to demand that Eurozone creditors should collect debt payments from the bank accounts of wealth Greeks who laundered and deposited in London, Zurich, Frankfurt, New York and elsewhere.

The principle of the LG should be “those who borrowed the loans and profited, should pay them.”

[...]

The LG should repudiate illegal debts (the vast majority) and renegotiate and roll-over the rest over an extended time frame, pending an economic recovery.
What should be recognized is that past Greek governments (despite being formally elected) engaged in illegitimate activity which prejudiced the sovereignty, productive capacity, and livelihood of an entire people.

What is not acceptable is to force an entire people to sacrifice their lives because a minority of Greeks borrowed and didn’t invest or pay their debts to overseas creditors. Currently the kleptocratic millionaires are given “cover,” and their illicit multi-billion Euro bank accounts and real-estate holdings are protected by the banks demanding payments from the Greek government. Their current demands are based on a savage demolition of living standards for a whole people.

it will be very, VERY interesting to see the outcome of the greek election tomorrow...


Labels: , , , , , , , , , , , , ,

Submit To Propeller


[Permalink] 0 comments

Tuesday, June 05, 2012

Max Keiser: All hell is breaking loose

what the banks are really afraid of is a country standing up for itself...

max holds forth on rt...
In this episode, Max Keiser and co-host, Stacy Herbert, discuss all hell breaking loose as an electronics chain store stockpiles security shutters, capital flees Greece (and Spain) and Max proposes a love market. In the second half of the show Max talks to Detlev Schlichter, author of Paper Money Collapse, about the euro, the drachma, the dollar and gold.

Labels: , , , , , , ,

Submit To Propeller


[Permalink] 0 comments

Saturday, April 28, 2012

Stiglitz: Austerity is economic suicide

but for our super-rich elites, austerity is boom times...
Austerity Measures Leading Europe To ‘Suicide’, Nobel Economist Says
Nobel Prize-winning economist Joseph Stiglitz said Europe is in a “dire” situation as a focus on austerity pushes the continent toward “suicide.”

“There has never been any successful austerity program in any large country,” Stiglitz, 69, said in Vienna on Thursday. “The European approach definitely is the least promising. I think Europe is headed to a suicide. ”

Politicians across the 27 European Union members are implementing austerity measures totaling about 450 billion euros ($600 billion) amid a sovereign-debt crisis. At the same time the debt of the euro region rose last year to the highest since the start of the single currency as governments increased borrowing to plug budget deficits and fund bailouts of fellow nations.

If Greece was the only part of Europe that was having austerity, authorities could ignore it, Stiglitz said, “but if you have UK, France, you know all the countries having austerity, it’s like a joint austerity and the economic consequences of that are going to be dire.”

While euro-area leaders “realized that austerity itself won’t work and that we need growth,” no actions have followed and “what they agreed to do last December is a recipe to ensure that it dies,” he said, referring to the euro. “The problem is that with the euro, you’ve separated out the government from the central bank and the printing presses and you’ve created a big problem,” Stiglitz said, adding that “austerity combined with the constraints of the euro are a lethal combination.”

The economist said he sees a core euro area of “one or two countries” made up of Germany and possibly the Netherlands or Finland as the “likely scenario if Europe maintains the austerity approach,” he said. “The austerity approach will lead to high levels of unemployment that will be politically unacceptable and will make deficits get worse.”

Youth unemployment in Spain has been at 50 percent since the crisis in 2008 with “no hope of things getting better anytime soon,” said Stiglitz, who is a professor for economics at Columbia University. “What you are doing is destroying the human capital, you are creating alienated young people.” To push for growth, European leaders could refocus government spending to “fully utilize” institutions like the European Investment Bank, introduce taxes to improve economic performance and use balanced budget multipliers, he said.

what policies of severe austerity do is punish people for the greed pursued by their ruling super-rich elites... and as a result of that punishment, people are forced out of their homes and into menial wage jobs while the ruling class vacuums up ever more money and power... it's win-win for the ruling class and lose-lose for us peasants...

Labels: , , , , , , , ,

Submit To Propeller


[Permalink] 0 comments

Monday, February 13, 2012

Greece's death sentence

mike whitney... here's a teaser...
It’s just corporate pillaging gone haywire. Greece is a big pinata that’s just been cracked open and everyone is pushing and shoving to grab their fistful of candy.

by all means, go read it all, but stay close to the toilet in case of retching...

Labels: , , , , , , ,

Submit To Propeller


[Permalink] 0 comments

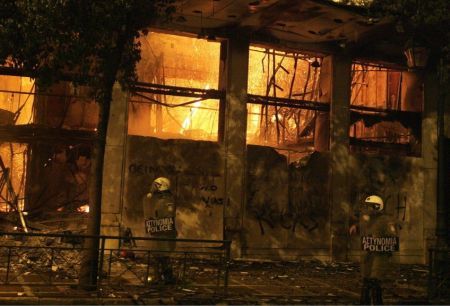
This is what happens when you push people too far and ask them to pay for your mistakes

this is what austerity looks like in greece...

from spiegel...


Photobucket

here's the article...
'The Troika's Policies Have Failed'

European Doubts Growing over Greece Debt Strategy

Labels: , , , , , ,

Submit To Propeller


[Permalink] 0 comments

Wednesday, January 25, 2012

Hedge funds are not really interested in an actual Greek rescue - only their profit matters

spiegel...
Hedge Funds Bet on Profits from Greek Debt Talks

The negotiations over the Greek debt haircut are becoming increasingly suspenseful, with euro-zone finance ministers and the IMF pushing investors to accept greater losses. Hedge funds, more than any others, stand to profit, and are betting that the voluntary debt rescheduling will fail.

Who will bleed for Greece? For weeks, private creditors like banks and insurers have been trying to negotiate a debt rescheduling with the country without success. Even when they seem close to agreement, it remains unclear if all creditors are on board. In particular, hedge funds that own Greek bonds could have a significant interest in ignoring the results of the negotiations, instead preferring to focus on an official national default.

Bank representatives assume in the meantime that many hedge funds are not really interested in an agreement. With a controversial investment strategy they have assured themselves of profiting with either a low level of Greek bad debts, or a complete Greek bankruptcy.

At issue are Greek bonds with a total volume of about €200 billion. How many are owned by hedge funds is unclear, but the amount is estimated to be about €70 billion (including other funds).

The bondholders are expected to voluntarily give up 50 percent of their claims. Another 15 percent is to be compensated with either cash or secure bonds of the European rescue fund EFSF. The remaining 35 percent should come in the form of new Greek bonds, that will likely reach maturity in 30 years.

The amount of money the creditors will actually have to give up depends on the interest rates on the new bonds. The Institute of International Finance (IIF), which is leading the negotiations with Greece, is insisting on an average of at least four percent. The euro-zone finance ministers and the International Monetary Fund (IMF) have instead insisted on rates lower than four percent, in order to make the burden on Greece more bearable. The banks calculate that this means they would actually lose closer to between 70 and 80 percent of their claims, and they are balking.

'Not Worried About Their Public Image'

For some hedge funds, the fight over interest rates has given them more incentive to push for a breakdown of the proposed plan. Officially, they are in the same boat as the banks and insurance companies. But in reality their interests are vastly opposed. "Hedge funds don't need to worry about their public image," one banker says. Their reputation has already been destroyed. Therefore, they can be relatively cavalier in gambling with the possibility of a Greek bankruptcy.

In an internal analysis of the German Savings Banks Association (DSGV), which represents the public banks, the hedge funds come off fairly badly. Withttp://www.blogger.com/img/blank.gifh the financial investors "only the performance" is most important. There is "hardly a political or economic corrective factor," such as long-term customer or contractual relations, the analysis says. Therefore, "one can conclude that they are not really interested in an actual Greek rescue."

i honestly don't think the hedge funds have EVER been seriously concerned about their reputation... it's always been about money - how much can be grabbed and how fast - and woe to anybody who gets in the way... matt taibbi's metaphor of a giant vampire squid glued firmly to the face of not only humanity but also to the planet is apt... they will suck the life out of anything and everything as long as there is money to be made...

Labels: , , , , , , ,

Submit To Propeller


[Permalink] 0 comments

Friday, December 09, 2011

Democracy under attack around the world - "These are very dangerous times"

yes, these are very dangerous times... i can't shake the feeling that we are on the cusp of something very, very big, something that could go either way - continuing down the dark path we're currently on or perhaps something wonderful that will surprise us all... it's a tipping point, for sure...

thom hartmann...

A year ago - if you would have asked the proud people in Italy - if their elected Prime Minister could be replaced by an unelected bankster to impose harsh austerity measures on them without a single vote - they would have called you crazy. Similarly - if you would have asked the Greeks - the cradle of democracy - if their elected Prime Minister could be run out of office for just asking for a national referendum on a bailout - and replaced by a bankster - they too would have called you crazy. Yet - that's exactly what's happened - and is continuing to happen in Europe.

Democracy is under attack around the world - including the United States - where Republican Governor Rick Snyder in Michigan has given himself the power to appoint unelected "financial managers" to take over cities struggling with budget deficits - fire elected city council officials - void union contracts - and sell off large chunks of cities to private corporations. Other Republican governors are thinking this is a good idea.

These are very dangerous times.

there's a lot of stuff piling up against the dam right toward the end of the year... if you're quiet, you can hear the cracks spreading...

Labels: , , , , , , , , ,

Submit To Propeller


[Permalink] 0 comments

Monday, November 28, 2011

The Euro Zone is on the edge [UPDATE]


spiegel...
A Continent Stares into the Abyss

Fear is spreading through the financial markets as investors pull their money out of the crisis-stricken euro-zone countries. With Chancellor Angela Merkel ophttp://www.blogger.com/img/blank.gifposed to using the ECB's firepower to solve the crisis, the monetary union appears increasingly in danger of breaking apart. Some economists are even arguing for Germany to reintroduce the deutsche mark.

mm-hmmmm...

[UPDATE]

it looks like barack is worried about the global economy his re-election prospects...

from the guardian [emphasis added]...

Barack Obama is to press European Union officials to reach a definitive solution to their sovereign debt crisis, which is emerging as a major 2012 US election worry.

As Germany and France scramble to tighten budget controls across the eurozone, the European council president, Herman Van Rompuy, and the European commission president, José Manuel Barroso, will face tough questions from Obama at the White House on Monday on how much longer the crisis might go on.

No breakthroughs are expected from the meeting, which will not include the European heads of state who need to make crucial decisions about the future of the 17-nation currency union.

But Van Rompuy and Barroso wield influence as heads of key EU institutions at the heart of efforts to fight the crisis, which has thrown the future of the eurozone into doubt at a moment of weakness for the global economy.

what's at the root of barack's 2012 worry, i wonder...? is it merely the prospect of losing votes or that the super-rich elites who pump vast amounts of cash into obama's campaign coffers might either not have enough to throw his way or, if they do, might not be willing to fork it over...?

Labels: , , , , , , , , ,

Submit To Propeller


[Permalink] 0 comments

Wednesday, November 23, 2011

The size of the IMF resources are absolutely not sufficient to bailout Europe which is a slow-motion train wreck


nouriel roubini blog...
Roubini said that the IMF does not have enough resources to save Europe and that now the contagion is spreading to the rest of Europe , the size of the IMF resources are absolutely not sufficient to bailout Europe , Italy and Spain alone are in 3 trillion euro public debt problem equivalent to 4 trillion US Dollars .... money alone is not going to resolve the problems in Europe Roubini explains , Europe is a slow motion train wreck he added ... "The contagion has now gone viral, cross Atlantic and global." Roubini says.

Photobucket

Labels: , , , , , , ,

Submit To Propeller


[Permalink] 2 comments

Tuesday, November 22, 2011

The economies of the European countries explained

a classic variation on the old abbott and costello "who's on first" routine...

clarke and dawe...


keep in mind that this was recorded almost two years ago...

Labels: , , , ,

Submit To Propeller


[Permalink] 0 comments

Sunday, November 20, 2011

This week presents the most extreme convergence of events the world has seen since September of 2008

james howard kunstler...
The Blue Bus Is Calling Us

Labels: , , , ,

Submit To Propeller


[Permalink] 0 comments

Friday, November 18, 2011

Roubini - break-up of the Euro Zone

the contagion is spreading...

Labels: , , , ,

Submit To Propeller


[Permalink] 0 comments

Sunday, November 13, 2011

An elevated risk of the collapse of the Euro

a viewpoint you definitely won't see on u.s. news media...

from ireland's tv 3...

Ireland's Financial Expert Eddie Hobbs advising people to get out of the Euro as it is going to collapse.


it's time to stock up on popcorn...

Labels: , , , , , , ,

Submit To Propeller


[Permalink] 0 comments

Thursday, November 10, 2011

Italy is TBTF Too Big to Fail but it is also TBTS Too Big To Save [UPDATE] [UPDATE II]


nouriel roubini...
The worst case scenario for Italy is inevitable

Clearly unsustainable.

and thus spake dr.doom...

[UPDATE and BUMPED]

from the financial times...
Nouriel Roubini: Why Italy’s days in the eurozone may be numbered

With interest rates on its sovereign debt surging well above seven per cent, there is a rising risk that Italy may soon lose market access. Given that it is too-big-to-fail but also too-big-to-save, this could lead to a forced restructuring of its public debt of €1,900bn.

That would partially address its “stock” problem of large and unsustainable debt but it would not resolve its “flow” problem, a large current account deficit, lack of external competitiveness and a worsening plunge in gross domestic product and economic activity.

i don't know about you, but i'm getting the distinct feeling that something really, really big is about to happen...

[UPDATE II and BUMPED]

the collapse of the euro zone appears to be getting closer and closer... accordingly, i've added two more popcorn-eating icons to graphically demo just how interesting this whole thing is getting...


from the ft...
Market spikes eurozone’s guns

This week’s market upheaval in Europe has made it difficult to increase the firepower of the eurozone’s €440bn rescue fund to the €1,000bn that the bloc’s leaders had hoped for, the fund’s chief executive said on Thursday.

Investors have fled from bonds issued by highly indebted countries. Luring them back by offering insurance on losses – the centrepiece of a plan agreed in Brussels on October 26 – would now probably use up more of the fund’s resources, Klaus Regling, head of the European financial stability facility, said.

His concerns underline Europe’s difficulties in putting in place mechanisms to contain the sovereign debt crisis and, if necessary, help Italy cope with soaring refinancing costs.

pull up a chair... get comfy... we just might be about to witness an historic economic collapse which, if it does happen, is going to have a domino effect that we can't even imagine...

Labels: , , , ,

Submit To Propeller


[Permalink] 0 comments

Monday, November 07, 2011

Significant risk of a Eurozone breakup

roubini prognosticates...

There is a “significant risk of a Eurozone breakup,” sources say Roubini told a handful of select party guests recently, reports the Business Insider. Adds the economist, if the Eurozone goes under, “everything around the world goes sour.”

Roubini has claimed that in the past he correctly predicted both the housing market crash and the worldwide recession, the aftermath of both is still evident in the crises across the globe. For his forecasting, Roubini has earned the title “Dr. Doom” from members of the media, who look to him for economic outlook and have been met with not-so-optimistic — and correct — assumptions from the analyst in the past. As the American economy continues to show slumping statistics and the unemployment rate stays at or above a stagnant 9 percent for months, a collapse across the pond could cause a catastrophe for the world economy.

Sources say Roubini announced, "If the Eurozone blows up, it all gets worse."

Less than two weeks ago, Roubini had predicted that the odds of a eurozone collapse were one-in-two.

“Unfortunately, in my view there is a risk, at least a 50 percent probability, that in the U.S., in the eurozone, in the United Kingdom, and in most advanced economies, the future in the next 12 months might suggest a recession, a downturn, rather than reacceleration of growth,” Roubini said on October 24 to Bloomberg.


i hate to endlessly repeat myself but i sure as hell do wish this damn house of cards would just go ahead and collapse already...

Labels: , , , ,

Submit To Propeller


[Permalink] 0 comments

Thursday, November 03, 2011

Disappointing - Greece cancels referendum

so much for democracy...
George Papandreou, Greek prime minister, has scrapped a controversial plan to hold a referendum on the heavily indebted country’s membership of the European Union and eurozone.

no doubt somebody put the metaphorical gun to his head...

Labels: , , , , , , ,

Submit To Propeller


[Permalink] 0 comments

Wednesday, November 02, 2011

e.e. cummings: There is some shit I will not eat

a perfect quote for the greek situation...

robert kuttner...

Bravo Papandreou!

[...]

I am reminded of a poem by e.e. cummings about a conscientious objector named Olaf, which includes the epic lyric, “There is some shit I will not eat.”This, essentially, is what Prime Minister Papandreou is saying. If you want the Greeks to continue the belt-tightening, you cannot alter the terms of the deal by stealth.By involving his countrymen in the decision, Papandreou turns himself from agent of foreign austerity demands into a leader of the Greek people. The referendum will be sometime this winter, after the true terms of the deal are clear.Polls taken over the weekend show that some 59 percent of Greeks oppose what appear to be the terms of the latest deal, but over 72 percent want Greece to stay in the eurozone.If the International Monetary Fund, European Union, and European Central Bank are as good as their word and hold the bankers to the terms that were negotiated, we can expect Papandreou to urge Greek citizens to ratify the bargain. If, on the other hand, political and financial elites try to wriggle out, then the Greek people can draw their own conclusions—and we will all be in the uncharted waters of a likely default by a eurozone country.In the meantime, Papandreou is showing real leadership. It is about time someone stood up against the banker-led austerity consensus.

regardless of papandreou's past behavior, putting this critical decision in the hands of the greek people is the right thing to do... people in the u.s. certainly never got that opportunity with the bankster bailout in 2008...

Labels: , , , , , , , , ,

Submit To Propeller


[Permalink] 0 comments

Tuesday, November 01, 2011

Eurozone breakup shock larger than Lehman

nouriel roubini...
The Eurozone eventual breakup shock could be larger than the fall of Lehman in 2008

In my view, there's a significant probability, more than 50 per cent, that over the next 12 months there's going to be another recession in most advanced economies," "Whether you call it a double dip recession, a continuation of the first recession or a second recession doesn't matter, it's semantic.

In a situation where it becomes disorderly, with defaults by a number of countries and a resulting exit of a number of states from the eurozone and its eventual break-up, the shock that could occur ... could be as large, if not larger, than the fall of Lehman in 2008.

i've made a habit of listening to roubini...

Labels: , , , , ,

Submit To Propeller


[Permalink] 0 comments

Common equity in Bank of America is either worthless or very close to it and now Greece could be the tipping point

from rt...
European leaders reach a deal on the debt but if politicians decide there is no "credit event" and credit default swaps don't get paid -- it could leave large US banks "naked," according to independent analyst Reggie Middleton of Boom Bust blog. It could be a tipping point for Bank of America which he believes is insolvent and seeing pressure from all sides.


yeah, well, eurozone leaders THOUGHT they had reached a deal on greek debt...

reuters...

Greece risks meltdown after bailout vote bombshell

The Greek government faced possible collapse on Tuesday as ruling party lawmakers demanded Prime Minister George Papandreou resign for throwing the nation's euro membership into jeopardy with a shock call for a referendum.

Caught unawares by his high-risk gamble, the leaders of France and Germany summoned Papandreou to crisis talks in Cannes on Wednesday to push for a quick implehttp://www.blogger.com/img/blank.gifmentation of Greece's new bailout deal ahead of a summit of the G20 major world economies.

The euro and global stocks were pummeled on financial markets after the Greek move threw into question the survival of crucial efforts to contain the euro zone's sovereign debt crisis.

how very interesting - and perhaps even democratic - that papandreou actually thinks the citizens of greece should have a say...

a commentator, writing in spiegel, agrees with papandreou...

Papandreou Is Right to Let the Greeks Decide

It must be said right at the beginning: The Greeks will, for a change, decide for themselves how they and their country will move forward.

They have had no real opportunity to do so for quite some time. For about a year and a half, this once proud country has been under foreign administration; it is de facto no longer a sovereign state. The government's most important task has been dragging the austerity programs and structural reforms though parliament and implementing them. These are dictated by the strict troika of the EU Commission, the European Central Bank (ECB) and the International Monetary Fund. Otherwise there will be no more bailout money, and the country would go bankrupt.

To no longer be the master of their own finances, to be begging for money and ready to do almost anything for it -- this is as humiliating for penniless states as it is for poor people. It injures the soul, stirs up anger and creates desperation. Knowing that the situation is also largely self-inflicted only makes things worse.

That the Greek Premier Georgios Papandreou wants to consult his people on the financial restructuring of the country seems like an act of desperation appropriate to the dramatic principle of 'committing suicide in fear of death.' The voters will decide whether to endorse the decisions made in Brussels or not.

[...]

Until the referendum in Greece, there will be an intense debate about the two alternatives: Brutal rehabilitation within the euro zone or state bankruptcy with a reintroduction of the drachma.

It will demonstrate that it is not about the choice between hell and paradise. Both paths will be difficult and grueling. Each citizen must decide for themselves what they believe to be the better choice. They will consider whether they want to risk their assets with an exit from the common currency -- savings would be worth hardly anything in a return to the drachma.

But at least every Greek gets to decide, and can no longer complain about their government bowing to international demands. And even if the Greeks ultimately say no, and in the worst case scenario the country leaves the euro zone, the consequences seem less dicey than they did a year ago.

let the chips fall where they may... at least the greeks can once again lay claim to being a sovereign state rather than a wholly-owned subsidiary of the global banksters...

Labels: , , , , , , , , , , ,

Submit To Propeller


[Permalink] 2 comments